
Board members and executives in Culver City face real financial exposure every day. A single lawsuit or regulatory action can threaten your personal assets, even when you’re acting in good faith.
At Tower Insurance Associates, Inc., we help business leaders understand how Culver City directors liability insurance protects you from these risks. This guide covers what D&O insurance actually covers and why it matters for your leadership team.
What D&O Insurance Actually Protects
Directors and officers liability insurance covers three distinct areas that protect your personal finances when board decisions go wrong. First, it shields your personal assets when you face a lawsuit individually for actions taken in your role as a director or officer. If a shareholder claims you breached your fiduciary duty or made a negligent business decision, D&O insurance pays defense costs and settlements directly, preventing creditors from coming after your home, savings, or investments. Second, the policy covers employment practices claims including wrongful termination, discrimination, and harassment allegations.
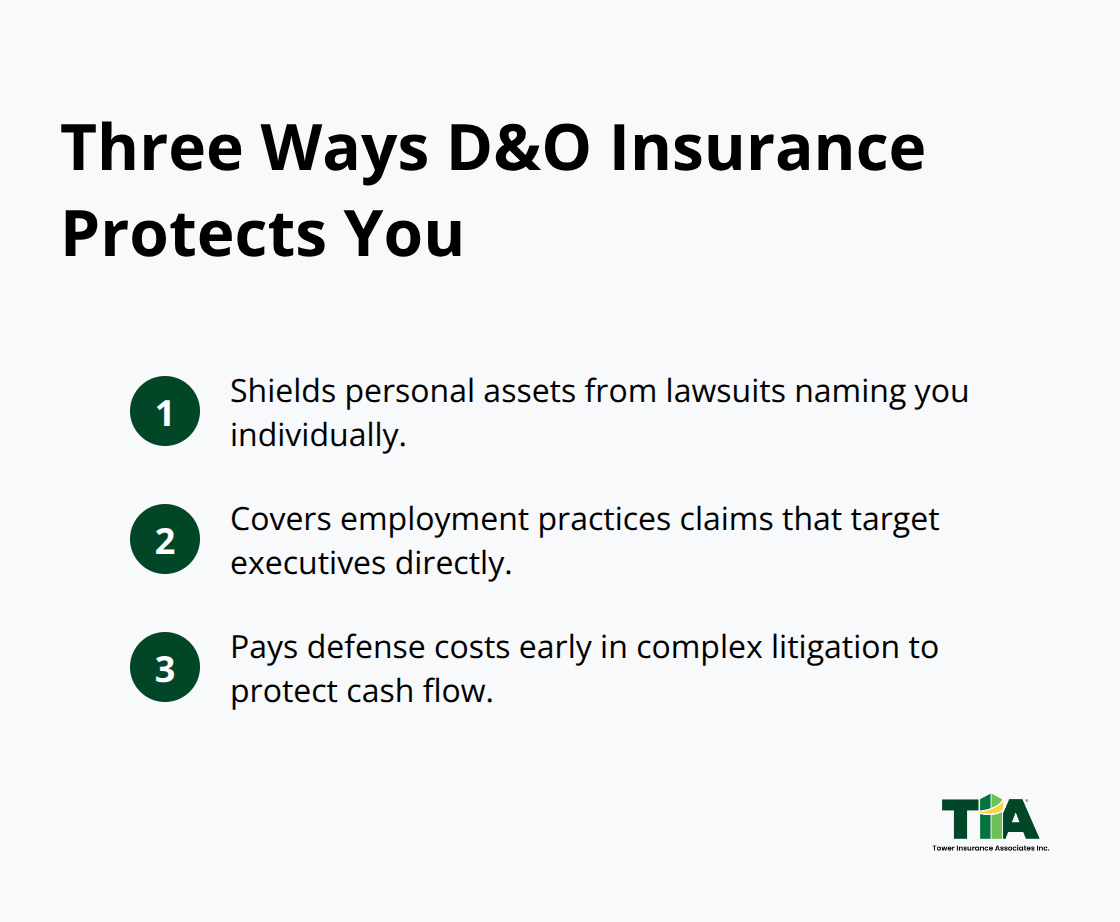
Employment discrimination claims increasingly target individual executives personally, not just the company. Third, D&O insurance covers the substantial legal expenses that accumulate before any settlement or verdict. Defense costs alone can reach $100,000 to $500,000 in complex litigation, and these bills come due immediately regardless of whether you ultimately win the case.
Personal Liability Protection Stands Apart From Company Coverage
Your company’s general liability or directors and officers errors and omissions policy won’t protect you individually when you’re named as a defendant. Courts frequently pursue personal assets of board members in shareholder disputes, and California courts have upheld claims against individual directors even when the company itself was insolvent. A D&O policy keeps personal liability separate from corporate liability, meaning your defense receives independent funding apart from company finances.
Employment Claims Target Individuals Directly
Wrongful termination and discrimination lawsuits increasingly name individual executives alongside the corporation. An employee claiming discrimination sues not just the company but also the hiring manager, the department head, and the CEO personally. D&O insurance covers your defense in these cases, which matters because employment litigation averages $150,000 to $300,000 in defense costs before trial. This protection applies even when the company itself faces no liability.
Defense Costs Accumulate Faster Than Most Directors Anticipate
Most directors don’t realize that defense costs mount immediately, often before insurance covers a settlement. Your attorney bills accumulate monthly, expert witnesses charge retainers, and court filings add up quickly. Without coverage, you pay these expenses out of pocket while hoping the case resolves. D&O insurance typically covers these costs from day one, protecting your cash flow during what can stretch into a years-long legal process.
The specific claims that land directors and officers in Culver City courtrooms reveal why this protection matters so much for your leadership team.
Claims That Target Culver City Directors Personally
Breach of Fiduciary Duty Exposes Directors to Substantial Personal Liability
Breach of fiduciary duty remains the most common claim against Culver City directors, and California courts take these violations seriously. When a director votes on a contract that benefits themselves without full disclosure, fails to attend board meetings regularly, or makes decisions without reasonable investigation, shareholders file lawsuits seeking personal recovery from board members. The California Corporations Code holds directors to a strict standard-you must act in good faith and in a manner you believe is in the corporation’s best interest.
A single board decision made without proper diligence can trigger years of litigation. Defense costs in fiduciary duty cases average $200,000 to $400,000 because these lawsuits require extensive document review, expert testimony about corporate governance standards, and depositions of multiple board members. Even when you ultimately win, you’ve already spent six figures defending yourself.
Employment Claims Name Individual Executives Directly
Wrongful termination and discrimination claims directly name individual executives far more often than most directors realize. An employee claiming they were fired for reporting safety violations or discriminated against based on age, race, or disability sues the company and simultaneously sues the CEO, the department manager, and the HR director as individuals. California’s strong employment protections mean these cases proceed aggressively-the state’s Department of Fair Employment and Housing received over 200,000 complaints statewide in 2024.
Your personal liability exists independently from the company’s liability, and your personal assets become a target even when the company settles. These cases move quickly from initial complaints into personal asset recovery proceedings, and without D&O insurance, your defense comes entirely from your own pocket while creditors wait to attach whatever judgment they win.
Financial Mismanagement Creates Rapid Personal Exposure
Directors who approve loans to themselves, fail to maintain proper accounting records, or ignore warning signs of embezzlement face personal liability for shareholder losses. California courts have awarded damages exceeding $5 million against individual directors in cases involving significant financial misstatement or self-dealing. These disputes transform from corporate governance issues into personal asset recovery proceedings within months.
The specific exposure you face as a Culver City director depends on your industry, company size, and board composition-factors that directly shape which D&O coverage limits you actually need.
Why Culver City Directors Face Personal Asset Exposure Without D&O Insurance
Your Personal Wealth Sits Exposed When Litigation Arrives
Culver City directors face a reality that many business leaders overlook until litigation arrives: your personal wealth sits exposed to creditors the moment a shareholder or employee files suit against you individually. California courts routinely pierce the corporate veil and pursue personal assets when directors face breach of fiduciary duty claims, and judges have consistently upheld judgments against individual board members even when the company itself declares bankruptcy. Without D&O insurance, a $2 million judgment against you personally means creditors can attach your home, investment accounts, and retirement savings.
The California Corporations Code does not protect your personal assets from liability you incur while serving on a board, and your homeowner’s insurance explicitly excludes business-related lawsuits. This gap between corporate liability and personal exposure has widened considerably as California’s regulatory environment intensifies. The state’s Department of Fair Employment and Housing, which oversees discrimination and wrongful termination claims, processed over 200,000 complaints statewide in 2024, and individual executives face named defendant status in the vast majority of these cases.
Regulators Target Personal Conduct Over Corporate Policy
Regulators increasingly target personal conduct rather than corporate policy, meaning your individual decisions about hiring, compensation, and workplace safety trigger personal liability exposure that standard business insurance simply does not cover. A single hiring decision you made without proper documentation can expose your personal assets to recovery proceedings, regardless of whether the company itself faces liability. Your personal conduct as a director creates independent legal exposure that corporate policies cannot shield.
Board Recruitment Becomes Harder Without Coverage in Place
Attracting strong board talent to Culver City companies has become markedly harder without D&O insurance in place, and this directly affects your company’s governance quality and decision-making capability. Experienced directors and executives increasingly demand confirmation that D&O coverage exists before accepting board positions, and many candidates now request proof of coverage limits before signing on. Companies without D&O insurance find themselves recruiting from a smaller pool of less experienced candidates, which compounds governance risks and creates a self-reinforcing cycle of weaker boards making riskier decisions.
The competitive pressure intensifies because qualified directors know their personal exposure and want contractual assurance that the company has funded their defense. Culver City businesses competing for board talent against larger corporations with established D&O programs face real recruitment disadvantages when they lack this protection. Tower Insurance Associates, Inc., an independent insurance agency in Culver City since 1961, can help you secure D&O coverage that meets market expectations and positions your company competitively when recruiting board members who understand their personal liability exposure.
Final Thoughts
D&O insurance protects your personal assets from the lawsuits that inevitably target board members and executives in Culver City. Without coverage, a single shareholder dispute or employment claim forces you to liquidate savings, refinance your home, or watch creditors attach retirement accounts. The financial exposure is real, the litigation costs are substantial, and Culver City directors liability remains your personal burden to bear.
Review your current coverage with a critical eye and ask your insurance broker whether your existing policies actually cover personal liability for directors and officers, or whether they only protect the corporation. Many business owners discover their general liability policies explicitly exclude board-level decisions and employment practices claims. Request specific information about coverage limits, defense cost provisions, and whether your policy covers defense expenses before any settlement or verdict.
We at Tower Insurance Associates, Inc., have helped Culver City business leaders secure appropriate D&O coverage since 1961. As an independent insurance agency, we represent multiple top-rated carriers and match your specific board composition and industry risks with coverage that actually protects your personal assets. Contact Tower Insurance Associates to evaluate your directors liability coverage and confirm your leadership team has the protection they need.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.